1. Executive Summary & Week in Review
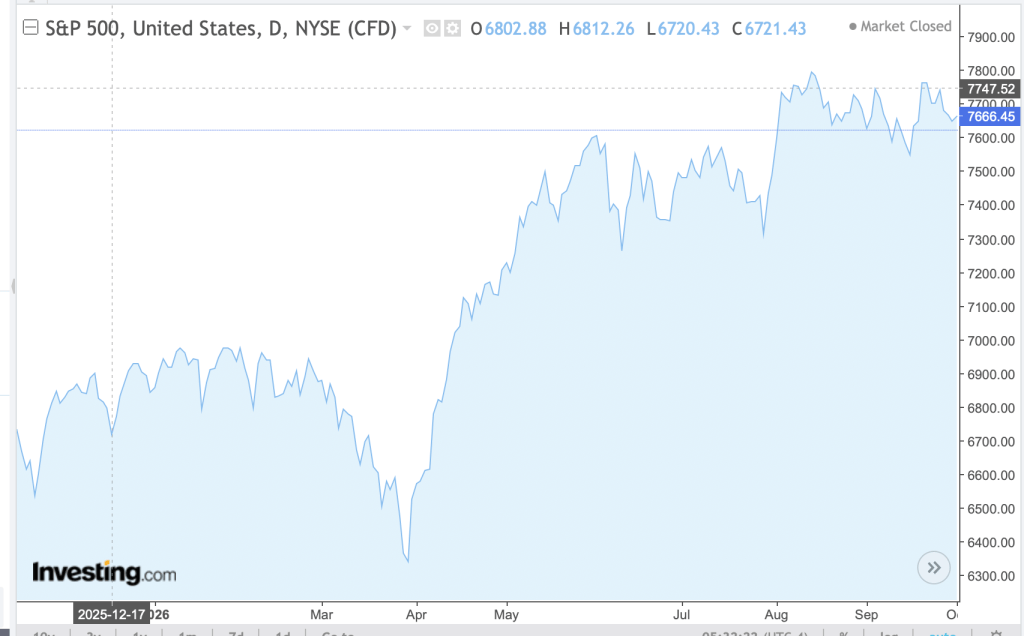
Global equities experienced notable volatility this week, characterized by sharp divergences across key sectors. The tech-heavy Nasdaq Composite and the S&P 500 faced selling pressure, primarily driven by valuation pullbacks in artificial intelligence (AI) and semiconductor stocks alongside rising energy prices. In contrast, defensive and consumer staple equities demonstrated relative resilience, reflecting cautious investor sentiment as the corporate earnings season accelerates.
2. Macroeconomics & Fed Watch
The macroeconomic backdrop this week was dominated by evolving expectations regarding Federal Reserve monetary policy and inflationary pressures:
- Interest Rate Path: Investors are scrutinizing the Federal Reserve’s upcoming policy trajectory following recent benchmark rate adjustments. While core inflation has shown signs of stabilization, energy market spikes have sparked concerns over headline price pressures.
- Treasury Yields: Bond yields remained sensitive to economic data releases, reflecting ongoing debates among market participants over whether the central bank will maintain higher-for-longer rates or signal further monetary easing going into 2027.
3. Stock Spotlight: Nvidia & The Semiconductor Sector
- Ticker: NVDA (Nvidia) / Semiconductor Industry
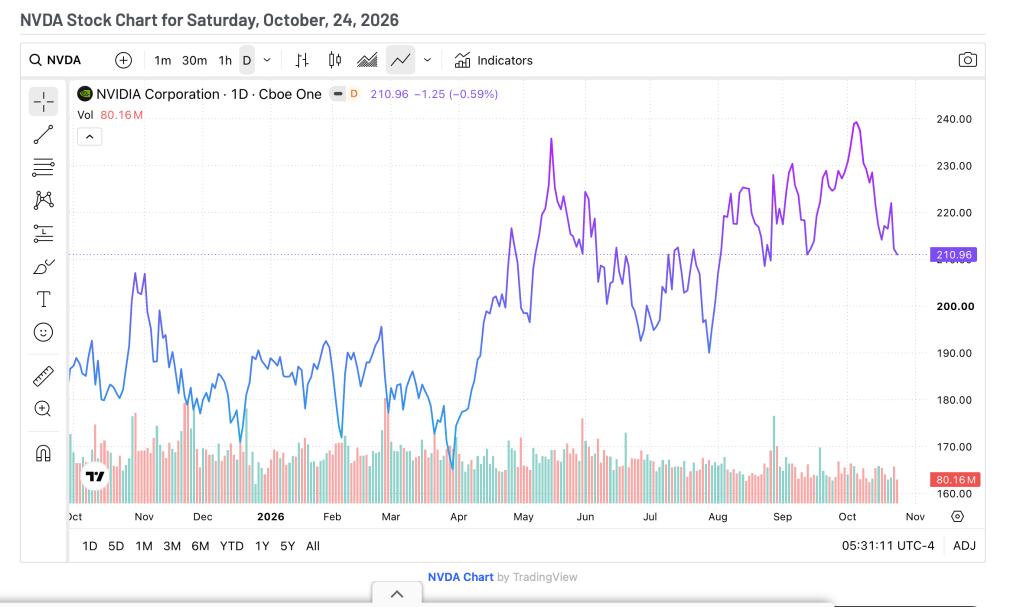
- Market Dynamic: The semiconductor industry, led by heavyweights like Nvidia, experienced notable downward pressure this week as investors locked in profits following sustained highs.
- Catalysts:
- Valuation Sensitivity: Market participants are reassessing capital expenditure returns across enterprise AI rollouts, leading to temporary multiple contractions.
- Energy & Infrastructure Costs: Surging energy prices and data-center power constraints have added a layer of operational scrutiny to hyper-scale cloud providers.
- Key Takeaway: Despite short-term price pullbacks, secular demand for next-generation compute infrastructure remains solid across enterprise workflows.
4. Student’s Analytical Perspective
From an economic viewpoint, this week’s price action highlights the delicate balance between macro liquidity and sector fundamentals.
Rather than viewing the tech selloff as a systemic breakdown, it reflects a healthy rotation from aggressive growth multiples into fundamentally defensive assets while markets absorb interest rate guidance. For long-term capital allocators, structural headwinds in energy and power capacity will likely dictate the next phase of tech capital deployment. Moving into November, corporate guidance from mega-cap earnings reports will be the primary litmus test for whether broader equity valuations can be sustained.
Disclaimer: This research note is prepared by TEENS CENSUS for academic and extracurricular research purposes only and does not constitute financial advice.


답글 남기기